Help getting to closing.
Down payment and closing-cost assistance reduces what qualified buyers need from their own savings.
 Real estate. Financing. A clearer first step.
FIRST-TIME BUYERS · METRO DETROIT
Explore financing and down payment assistance options, understand eligibility, and compare what they mean for your purchase.
You don’t need to have it all figured out. Tyson Reeves connects the home search and the financing, so you can start with a plan.
EXPLORE MY PROGRAM OPTIONSA few details. A personal follow-up from Tyson.
Start with the possibilities.
Build a plan around you.
01 / WHAT HELP IS AVAILABLE
First-time buyer programs solve different problems. The useful question is which one solves yours.
Some reduce the cash you need upfront. Others offer financing designed for eligible buyers. Statewide, local, community and lender programs each have their own requirements.
Down payment and closing-cost assistance reduces what qualified buyers need from their own savings.
First-time buyer mortgages offer features such as lower down payments or financing terms designed for eligible buyers. Compare the payment and the upfront costs together.
Your household income, savings, financing and the home itself determine which programs are available. Two buyers won’t always have the same options.
A CLOSER LOOK / MSHDA
Michigan’s MI Home Loan shows why the financing and assistance should be considered together. Eligible buyers can compare help with upfront cash against a lower mortgage rate.
HELP WITH UPFRONT CASH
7.125% MSHDA-set mortgage rate · 7.248% APR
A LOWER MORTGAGE RATE
6.500% MSHDA-set mortgage rate · 6.619% APR
MSHDA rates can change.
APR reflects the interest rate plus certain loan costs expressed as an annual percentage. It is not the mortgage interest rate.
One helps with cash today. The other offers a lower rate.
Compare the cash needed and monthly payment against your purchase priorities.
Need help beyond the numbers? I can work with you as your Realtor, Loan Officer, or both.
DOWN PAYMENT ASSISTANCE / BEYOND MSHDA
MSHDA is one source of help. Statewide, local, community and lender programs also serve eligible buyers. Assistance covers different combinations of down payment, closing costs and prepaid taxes and insurance, depending on program rules.
Share where you are starting. Tyson will help connect the programs to your purchase.
02 / WHAT IT MEANS FOR YOUR PURCHASE
First-time buyer status is one piece of eligibility. Eligibility depends on your household, the property and the loan program.
Two buyers considering similar homes may qualify for different options. Checking these details early gives your search a more useful starting point.
Answer a few quick questions so I can get a clearer picture of your qualification.
CASH NEEDED TO BUY
Your cash plan includes what you pay before closing, what you bring to closing and what you keep afterward.
Assistance reduces eligible upfront costs when you qualify. Account for deposits already paid and permitted credits so the same dollars aren’t counted twice.
The portion of the purchase price you pay upfront.
Lender, title and other charges to complete the purchase.
Initial insurance costs and funds needed for tax and insurance escrows.
Inspection fees are paid during the process. An earnest-money deposit is typically credited toward what you owe at closing.
Money you keep available after the purchase, including any reserves required by your loan.
Bring your price range, savings and preferred location. Tyson will help estimate the full picture and explain which amounts depend on the home, financing and program.
A FEW USEFUL ANSWERS
No. Some programs also serve repeat buyers. MSHDA's MI Home Loan is available to first-time buyers statewide and repeat buyers in certain targeted areas. Each program sets its own rules.
Some programs can. MSHDA's MI 10K assistance may cover eligible down payment, closing costs and prepaid expenses. Other programs may cover different costs, so we will check what applies.
Yes. It is a loan with no monthly payment. Repayment is deferred until events such as paying off the first mortgage, selling or refinancing, or no longer occupying the home.
You choose the home. It needs to meet the loan and assistance program's rules, which may include location, price and property requirements. Checking those early helps focus your search.
Start with your income, savings, price range and preferred location. Tyson can help compare the options and explain what needs to be checked. Final eligibility depends on the program and lender review.
Yes. An early review can clarify your cash needs, payment and eligible locations, so you can look at homes with a more useful plan.
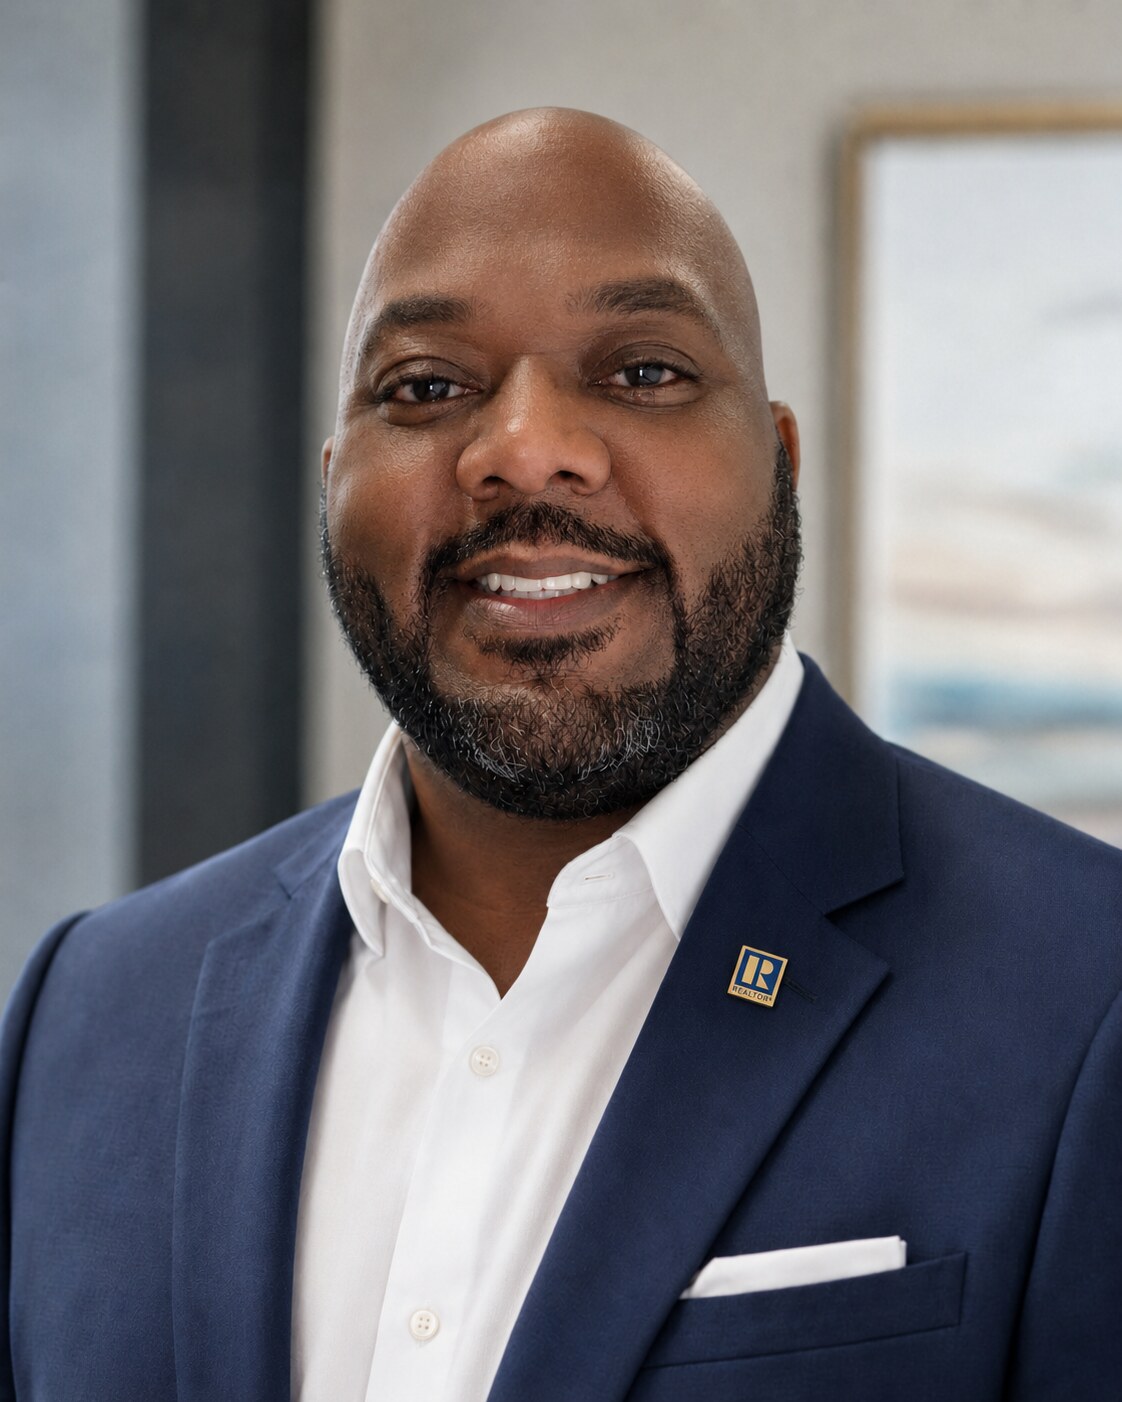
Tyson ReevesBroker / Owner, Stonehouse Realty
Real estate. Mortgage lending.
Property valuation.
03 / WHAT TO DO NEXT
You don’t need a finished plan to start the conversation.
Have a rough picture of your household income, monthly debts, savings, preferred location, price range and timeline. If you have spoken with a lender, bring what you already know.
Checking program eligibility early helps you understand the cash, payment and property requirements before you shop and make offers.
Tyson works in real estate and mortgage lending, with a background in property valuation. He will review your goals, discuss relevant options and explain the next step for checking financing and program eligibility.
YOUR FIRST STEP STARTS HERE
Share a few details about your purchase. Tyson will follow up to talk through programs, financing and a practical next step.
Still figuring out your budget or timeline? That’s a useful place to start.