3%
For qualifying HomeReady buyers
A smaller down payment for buyers who meet HomeReady requirements.
Borrower-paid PMI applies.
 The home. The offer. The mortgage.
CONVENTIONAL FINANCING · METRO DETROIT
Build a conventional mortgage around the home you want, your payment goals and the cash you want to use.
Compare your options with Tyson Reeves—a real-estate professional and mortgage loan officer who brings the purchase and financing together.
BUILD MY CONVENTIONAL PLANA few details. A personal follow-up from Tyson.
A home you want.
A mortgage that works with it.
01 / WHY BUYERS CHOOSE CONVENTIONAL
Conventional financing gives first-time and repeat buyers useful choices in how they buy.
Choose a down payment, compare 15-year and 30-year terms, and weigh the rate against upfront costs. Mortgage insurance changes with the down payment, too.
These decisions work together. The aim is a mortgage that supports your purchase goals, with a clear view of what you pay now and each month.
02 / HOW YOUR MORTGAGE COMES TOGETHER
The home, the payment and the cash you want to use all matter. Compare these options at the same purchase price to see the differences clearly.
A smaller down payment for buyers who meet HomeReady requirements.
Borrower-paid PMI applies.
Many conventional loans allow 5% down, for both first-time and repeat buyers.
Borrower-paid PMI applies.
Finances less than 5% down at the same purchase price and uses more cash upfront.
Reduced borrower-paid PMI applies.
Puts more cash into the purchase and gives you a larger equity position at closing.
Eliminates borrower-paid PMI.
THE PAYMENT / MORTGAGE INSURANCE
Monthly private mortgage insurance (PMI) adds to your payment when you put less than 20% down on standard conventional financing. Its cost varies with the borrower and loan.
Paying PMI lets an eligible buyer use a smaller down payment. Twenty percent down eliminates borrower-paid PMI. Compare the actual payment and cash required for each choice.
UPFRONT COST / RATE + POINTS
Points are an upfront cost paid in exchange for a lower mortgage rate. The decision depends on the cost, the rate difference and how long you expect to keep the mortgage.
Compare options with and without points. Look at how much you pay at closing and how much the lower rate saves over your expected time with the loan.
The rate and the cost belong in the same comparison.
PAYMENT + PAYOFF / LOAN TERM
Compare the same loan amount with each option’s actual rate. Choose a payment commitment and payoff timeline based on your priorities.
03 / CONVENTIONAL VS. FHA
Compare both loans using your purchase price, available cash and payment goals. Compare what you bring to closing, what you pay each month and how mortgage insurance works over time.
Use the same home and your actual loan options. The payment, cash required and total costs make the comparison useful.
Bring your questions. Tyson will help compare the choices together.
04 / PUTTING IT INTO YOUR PURCHASE
The price, offer, payment and cash required all shape the same decision.
Working through them together gives you a clearer basis for choosing a home and making an offer.
 Make room for your next chapter.
YOUR FIRST HOME
First-time buyers have conventional choices alongside FHA. Many loans start at 5% down, and qualifying HomeReady buyers may use 3%. Strong credit and income can make conventional financing a competitive option.
You can compare the loan and the home together from the start.
THE CASH YOU WANT TO USE
Some buyers prefer to put more cash into the purchase. Others prefer a smaller down payment. Either approach can support a strong purchase.
Compare the cash required—including closing costs—with the payment and offer you want to make. Your priorities guide the choice.
A FEW USEFUL ANSWERS
No. Many conventional loans start with 5% down, and qualifying HomeReady buyers can put as little as 3% down. Twenty percent down eliminates borrower-paid PMI.
Many conventional loans allow 5% down. Qualifying HomeReady buyers can put as little as 3% down. The minimum for your purchase depends on the loan and your eligibility.
It depends on the home, payment and cash you want to use. At the same purchase price, 10% uses less cash upfront and includes PMI. Twenty percent uses more cash and eliminates borrower-paid PMI.
Monthly PMI adds to your mortgage payment. The amount varies based on you and the loan. Compare the actual payment at different down payments to decide how much cash you want to put toward the purchase.
Compare the payment, down payment and mortgage insurance for both. Strong credit often makes conventional competitive. FHA offers more flexible credit requirements. The choice depends on your qualifications, purchase priorities and actual costs.
Compare the added upfront cost with the savings over the time you expect to keep the mortgage. Seeing both options helps you decide whether the expected savings justify the upfront cost.
A 30-year loan offers a lower required payment when comparing similar loans. A 15-year loan has a higher payment, faster payoff and less full-term interest. Weigh the monthly commitment against your preferred payoff timeline.
Yes. Many conventional loans start with 5% down, and qualifying HomeReady buyers can put as little as 3% down. Strong credit and income can make conventional financing a competitive option for a first home.
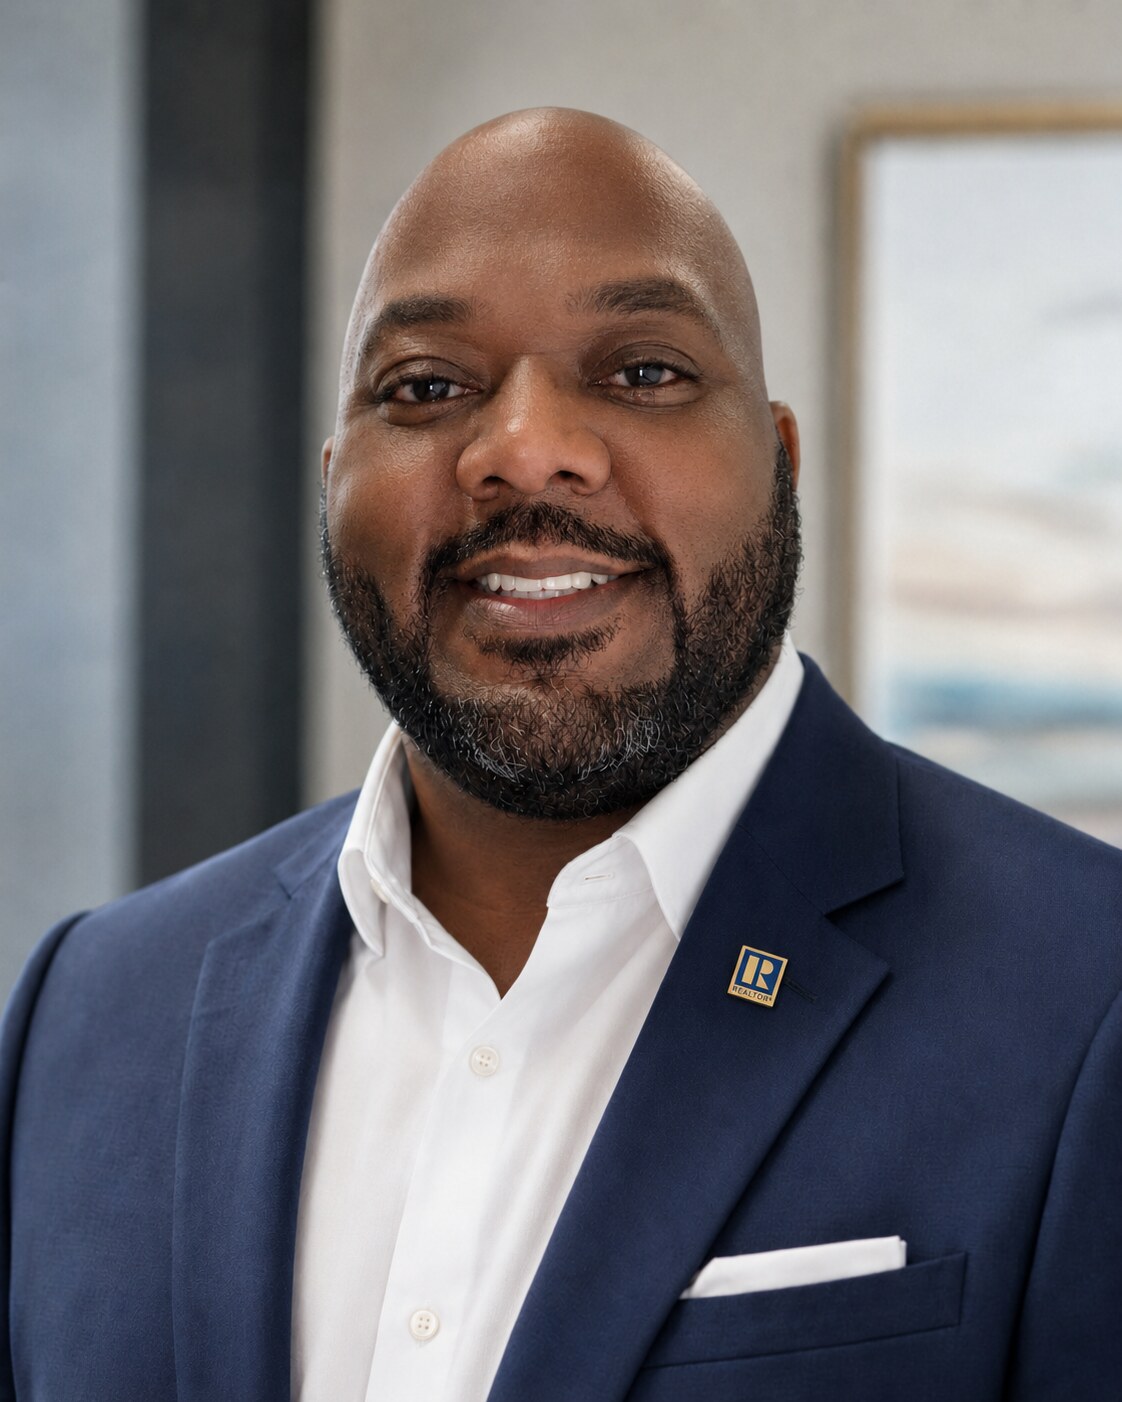
Tyson ReevesBroker / Owner, Stonehouse Realty
Real estate. Mortgage lending.
Property valuation.
ONE PLAN FOR THE HOME AND MORTGAGE
Talk through them with one professional who understands how they work together.
Tyson’s work in real estate, mortgage lending and property valuation connects the home you want with the decisions that help you buy it well.
Share your price range, timing and the choices you want to compare. Tyson will follow up with a practical next step.
YOUR NEXT STEP
Share a few details about your purchase. Tyson will follow up to compare mortgage options based on your goals.
Only your name, email and buying timeline are required. Add the other details if you have them.
Mortgage lending services provided through Everett Financial, Inc. dba Supreme Lending, NMLS #2129. Tyson Reeves, NMLS #1841849. Stonehouse Realty is not a mortgage lender, and clients are not required to use Tyson Reeves or Supreme Lending for financing.