 The home. The payment. The purchase.
BUYING POWER | METRO DETROIT
How much home can you realistically afford?
Start with your payment goals and the cash you want to use, then establish a price range you can shop with confidence.
Your income, debts, credit and financing shape the mortgage. The home’s taxes and insurance shape the payment. Bring them together to understand what you can realistically buy.
SEE MY BUYING RANGEA few details. A personal follow-up from Tyson.
The home you want.
The payment you’re comfortable with.
01 / WHAT CAN I REALISTICALLY AFFORD?
A useful range starts with the whole purchase.
What you qualify to borrow establishes one reference point. Your priorities determine how much you want to commit.
Start with the monthly housing cost you’re comfortable carrying, your available cash and your other commitments. Then connect those numbers to a mortgage and a home price.
Tyson Reeves brings real-estate and mortgage experience to the same conversation—so the home, the financing and the offer work together from the start.
EACH MONTH
Payment comfort
AT PURCHASE
Cash available
FOR THE LOAN
Financing options
02 / WHAT AFFECTS MY BUYING RANGE?
One payment.
More than one possible home price.
Two homes with the same price don’t always cost the same each month.
The interest rate, loan term and down payment affect your mortgage payment. Property taxes and homeowners insurance add to the monthly cost. Include mortgage insurance and association dues when they apply.
That’s why the same monthly budget supports different home prices depending on the property and how you finance it.
LOOK BEYOND THE LIST PRICE
Loan payment
+ taxes + insurance
Compare the total monthly cost.
INCOME + MONTHLY OBLIGATIONS
What’s coming in.
What’s already going out.
Lenders consider your income alongside the debt payments you already carry. Car payments, student loans and credit cards leave less room for a mortgage payment—even with a strong income.
Your own budget matters, too. Childcare, everyday expenses, savings and home upkeep belong in the amount you’re comfortable spending.
CREDIT + FINANCING
What you qualify for depends on the full picture.
Your credit profile affects the financing terms available to you. Income, debts, assets, the loan program and the property all factor into qualification.
Compare the actual rate, loan term and mortgage insurance together. A maximum loan amount is a limit to understand, not a spending target.
SEE YOUR REALISTIC BUYING RANGE
Answer a few quick questions so I can help establish your buying range and understand your payment goals. This check starts a planning discussion; lender preapproval is a separate step before serious home shopping.
DOWN PAYMENT + CASH NEEDED
Decide what to put in.
And what to keep.
A larger down payment reduces the amount borrowed at the same home price. It also changes the monthly payment, mortgage insurance and financing options.
But the down payment isn’t all the cash needed to buy. Allow for closing costs and upfront taxes and insurance, then consider what you want available after the move.
Compare the whole purchase.
Look at the cash required and the monthly payment side by side. A larger down payment isn’t automatically the better choice.
Bring your numbers into focus.
Share what you know. Tyson will help connect your payment, cash and financing to a realistic buying range.
The goal is a home you want.
And a purchase that makes sense.
03 / TURN THE NUMBERS INTO A HOME SEARCH
Know your range.
Shop with purpose.
The mortgage range, the homes you tour and the offer you make should belong to the same plan.
An initial buying-range discussion is a planning step, not lender preapproval. If you are financing the purchase, establish preapproval before serious home shopping. Then evaluate specific homes using their taxes, insurance and financing costs.
Then consider the offer price and terms with a clear view of both the monthly commitment and the cash needed to close.
A focused search. A considered offer.
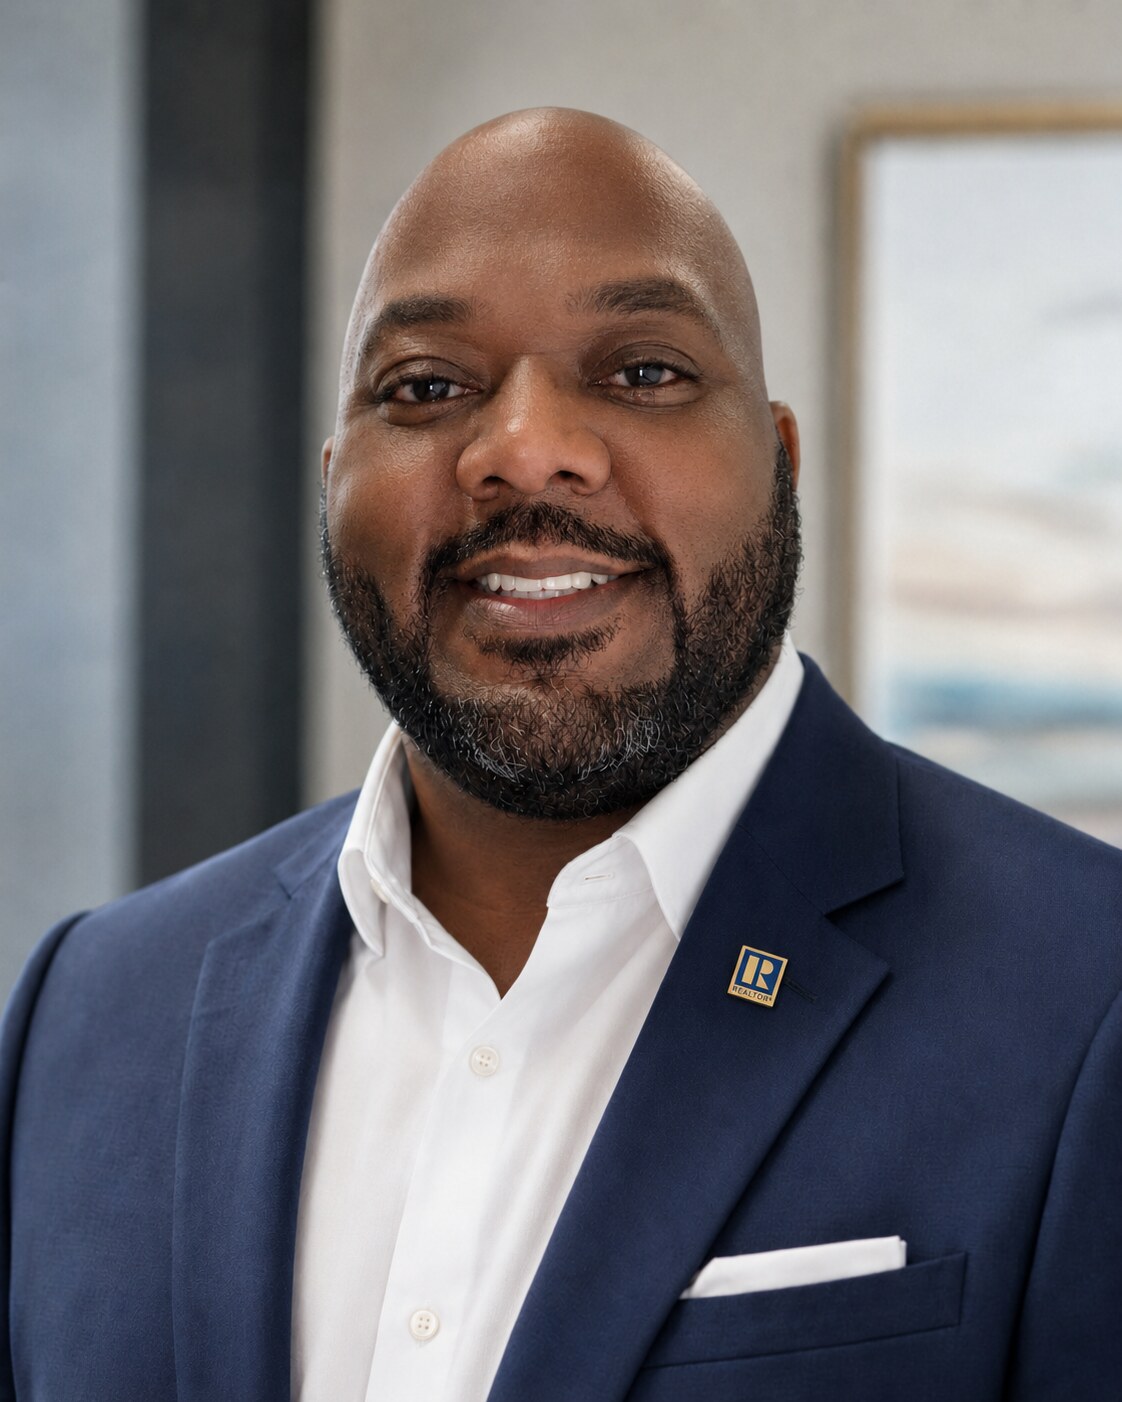
Tyson ReevesBroker / Owner, Stonehouse Realty
Real estate. Mortgage lending.
Property valuation.
ONE CONVERSATION. MORE OF THE PICTURE.
The home. The payment.
The financing. The offer.
Talk through the purchase with someone who understands how the pieces fit.
Tyson’s work in real estate, mortgage lending and property valuation brings the property and the numbers into one conversation. You get a clearer starting point for what to buy and how to approach it.
You don’t need every number ready.
Start with what you know. The next step is a personal conversation about your range and the purchase you have in mind.
YOUR NEXT STEP
Let’s find your
buying range.
Share a few details. Tyson will follow up to review your payment goals, available cash and buying range.
Only your name, email and buying timeline are required. Add the other details if you have them.